
Backend
NestJS
A structured way to build back ends on Node.js, so large business systems stay organised, testable and easy to hand over.
Used for
- Business app back ends
- SaaS platforms
- Marketplaces
- Admin panel back ends
Lending software
Origination, servicing and collections in one lending platform, configured for your products and partners.
At a glance
What it is
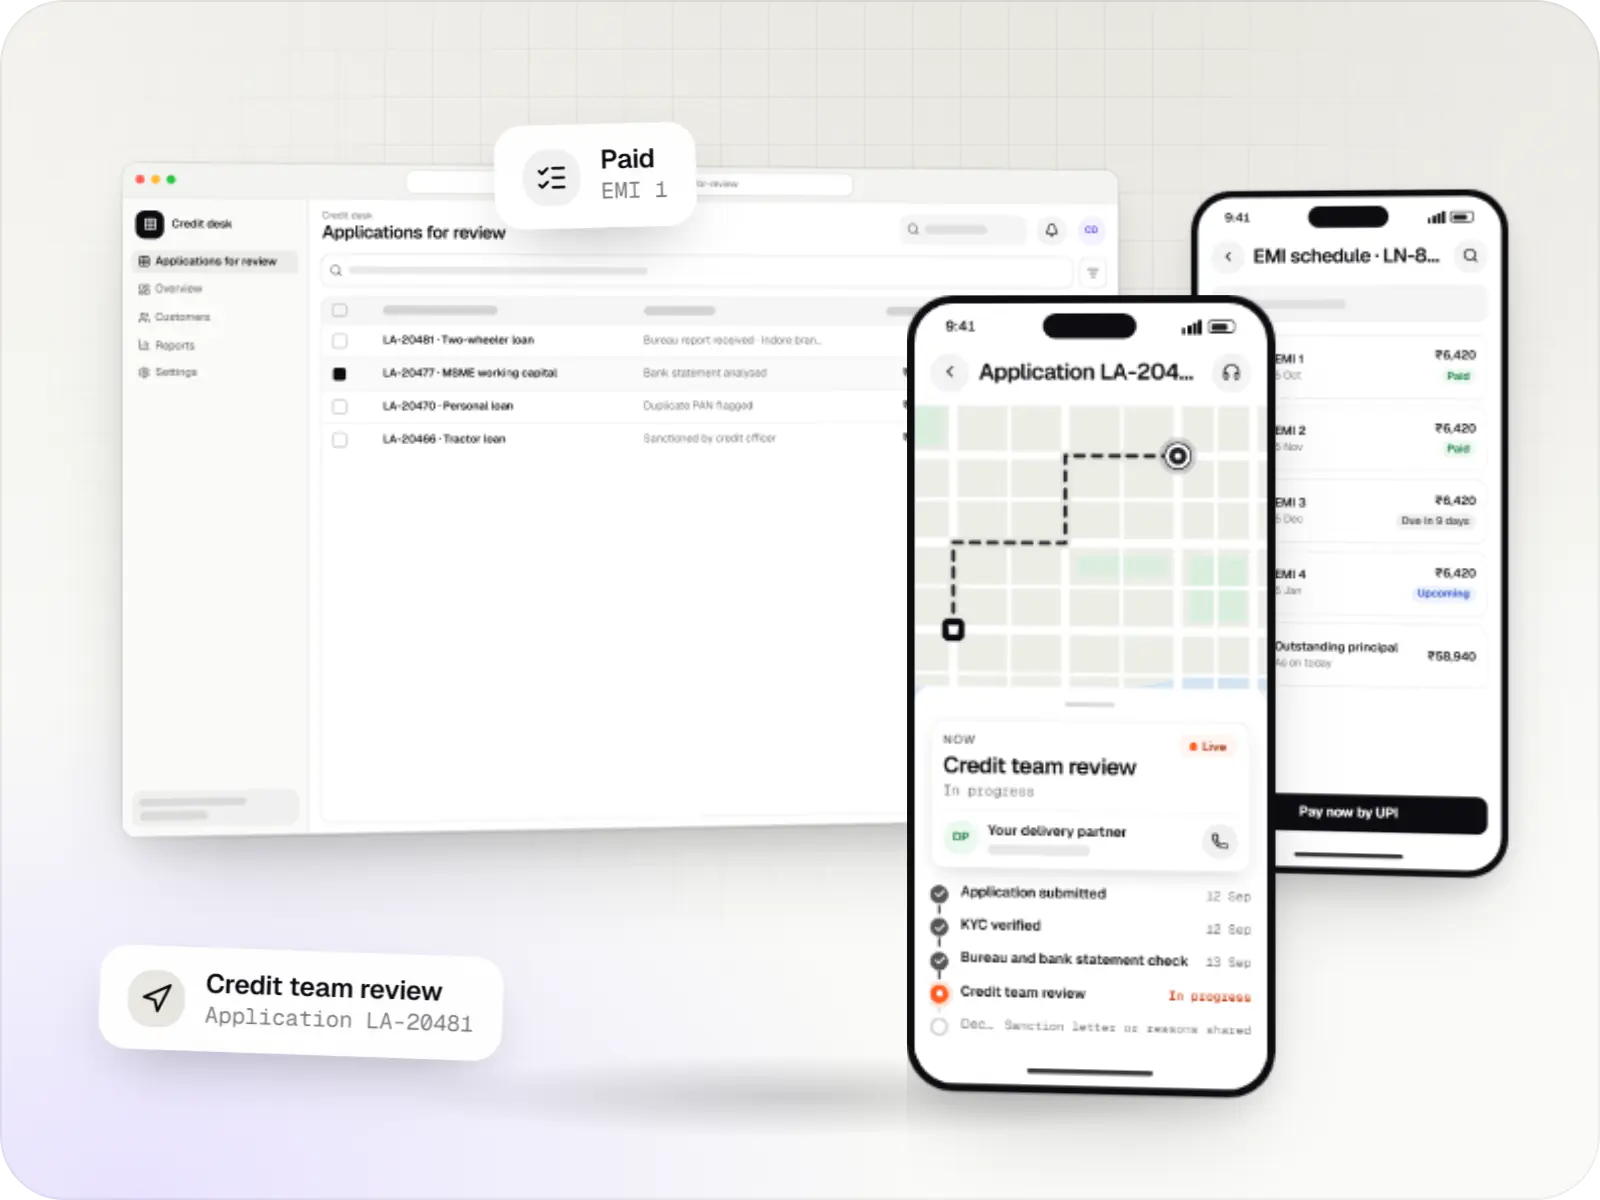
Custom loan origination and loan management software covering applications, underwriting, disbursal, EMIs, collections and reporting.
Flutter and the related logo are trademarks of Google LLC. We are not endorsed by or affiliated with Google LLC.
How to start
Tell us what you need in your own words. You talk to the developers who would build it and get a written, line-item estimate.
Get a project estimateLoans are long-lived records. A loan created today may be serviced for years, through part-payments, restructuring and collection cycles, and mistakes in interest accrual or charges compound over that life.
We build lending platforms around a loan ledger that records every accrual, charge, payment and adjustment, with product rules held in configuration. New products, such as a different tenure, repayment frequency or co-lending partner, can then be added without rewriting the core.
Challenges
Schedules, part-payments and overdue calculations maintained by hand drift from bank records.
Disclosure formats, penal charge rules and reporting needs change, and hard-coded systems lag behind.
Splitting collections and interest between partners loan by loan becomes a monthly exercise.
Field visits, promises to pay and cash receipts are not recorded in time.
What is included
Platform: Web app
Platform: Web app
Platform: Android app
How it works
Credit policy, KYC levels and disclosures are set by the lender and its compliance advisers in line with RBI guidelines; the software applies them consistently and records every decision.
The applicant submits details and documents, and duplicate checks on PAN, mobile number and bank account run immediately.
Identity is verified through licensed providers, and a bureau report and bank statement analysis are pulled with consent.
Eligibility rules and scorecards set by the lender prepare a recommendation; a credit officer makes the decision, which the system records with reasons.
If the loan is sanctioned, the borrower reviews the key fact statement, signs the agreement digitally and registers an e-NACH or UPI AutoPay mandate.
Funds go directly to the borrower's bank account, and the repayment schedule is created in the loan ledger.
Mandates are presented on due dates, overdue cases go to collections, and the loan closes with a no-dues certificate.
Platforms
Credit and operations teams use a web app; borrowers and field collectors use phone apps for Android.
Browser-based applications with logins, roles and workflows, such as customer portals, SaaS products and internal tools.
Apps for Android phones and tablets, tested on budget and mid-range devices and published on Google Play or privately.
Back-office panels for operations, support and finance teams: orders, users, content, reports and permissions.
Technology
Chosen for exact interest and charge calculations, dependable scheduled jobs and records that auditors can trace.
Backend
A structured way to build back ends on Node.js, so large business systems stay organised, testable and easy to hand over.
Used for
Backend
A programming language for AI features, data processing and automation: the engine behind document reading, reports and smart search.
Used for
Data
A reliable database for the records your business runs on: orders, payments, bookings and stock, kept accurate and easy to report on.
Used for
Data
Keeps frequently used data in fast memory, so apps stay quick on busy days and live features like order tracking feel instant.
Used for
Web
Builds interactive screens in the browser, such as dashboards, admin panels and portals, that respond instantly as your team works.
Used for
Mobile
Build Android and iOS apps from one shared codebase, so you launch on both platforms faster with a consistent experience.
Used for
Cloud & DevOps
Cloud hosting for your app, website and data, with data centres in India and room to grow when traffic rises.
Used for
Flutter and the related logo are trademarks of Google LLC. We are not endorsed by or affiliated with Google LLC.
Integrations
Bureau pulls and periodic data submissions in the formats bureaus require.
Identity verification through licensed providers.
Consent-based bank data and cash-flow analysis.
Mandate registration and presentation through a sponsor bank or aggregator.
Digitally executed loan agreements.
Disbursal straight to the borrower's bank account.
Privacy & security
Your compliance team maps RBI's digital lending requirements, such as key fact statements, direct disbursal and cooling-off periods; we implement and document them.
Borrower apps avoid contacts, media and call logs, collecting only what the journey needs, with consent.
Encrypted borrower data, masked identifiers, and second approval on sanctions, waivers and write-offs, all logged.
Dedupe on PAN, mobile and bank account, with alerts on unusual application patterns.
Plain-English glossary
Product preview
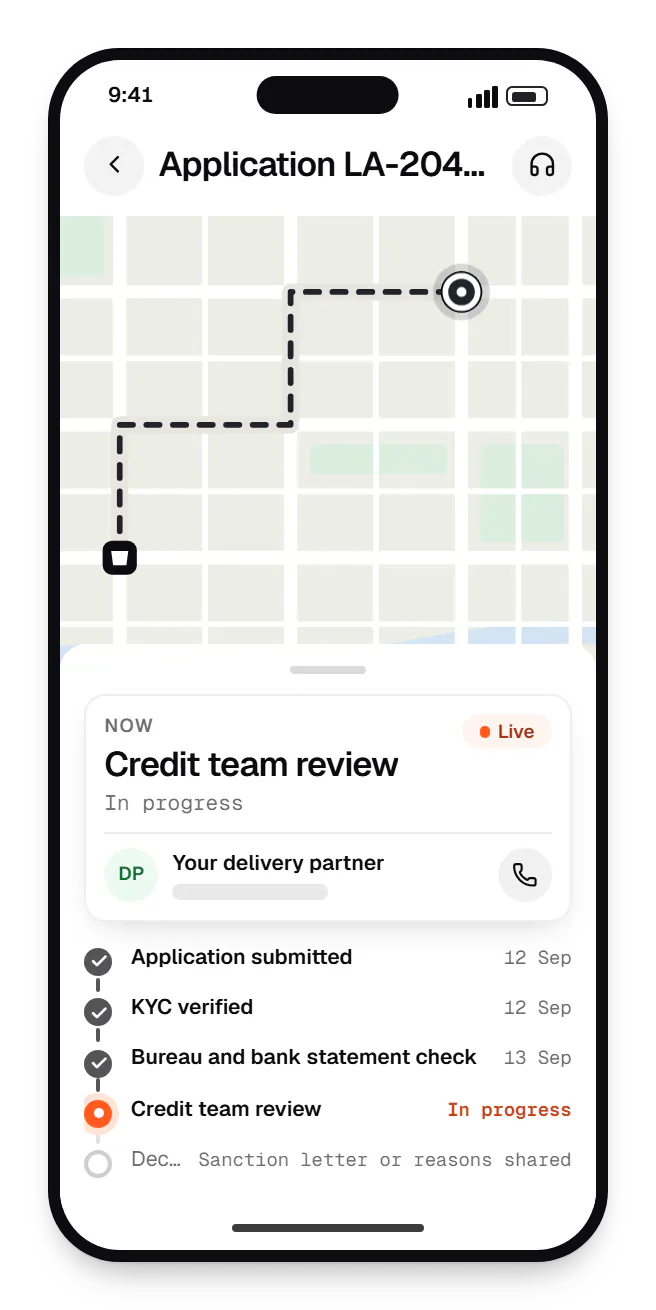
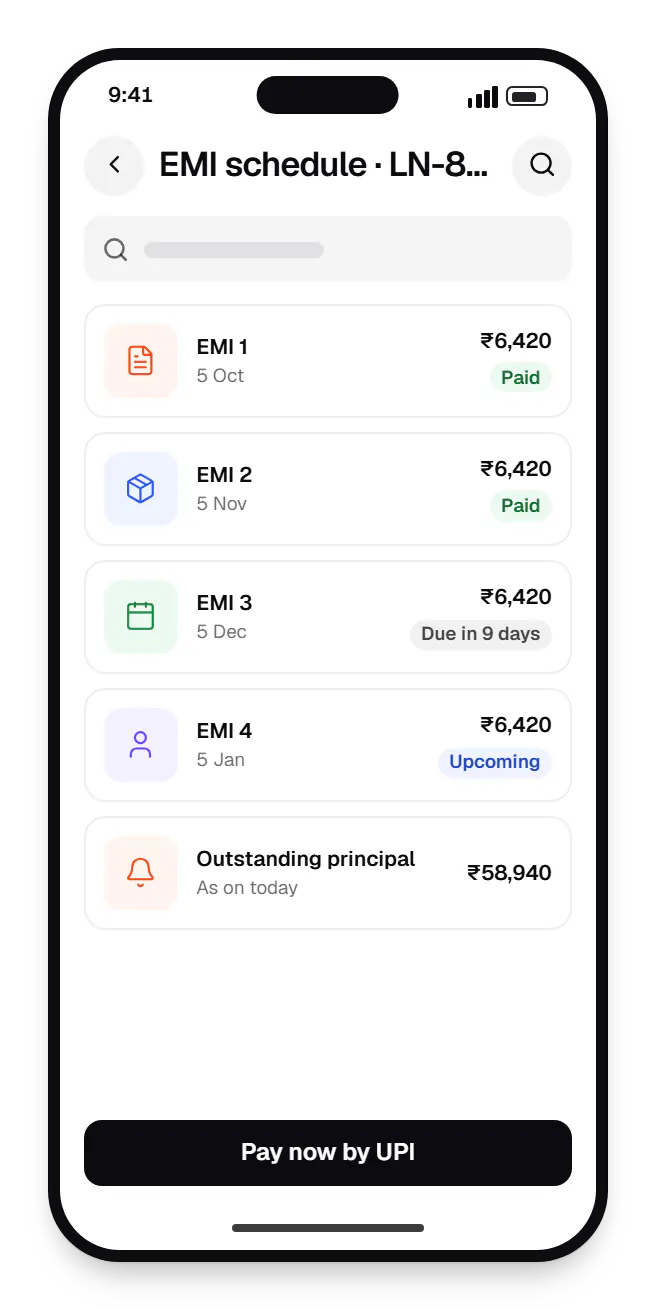
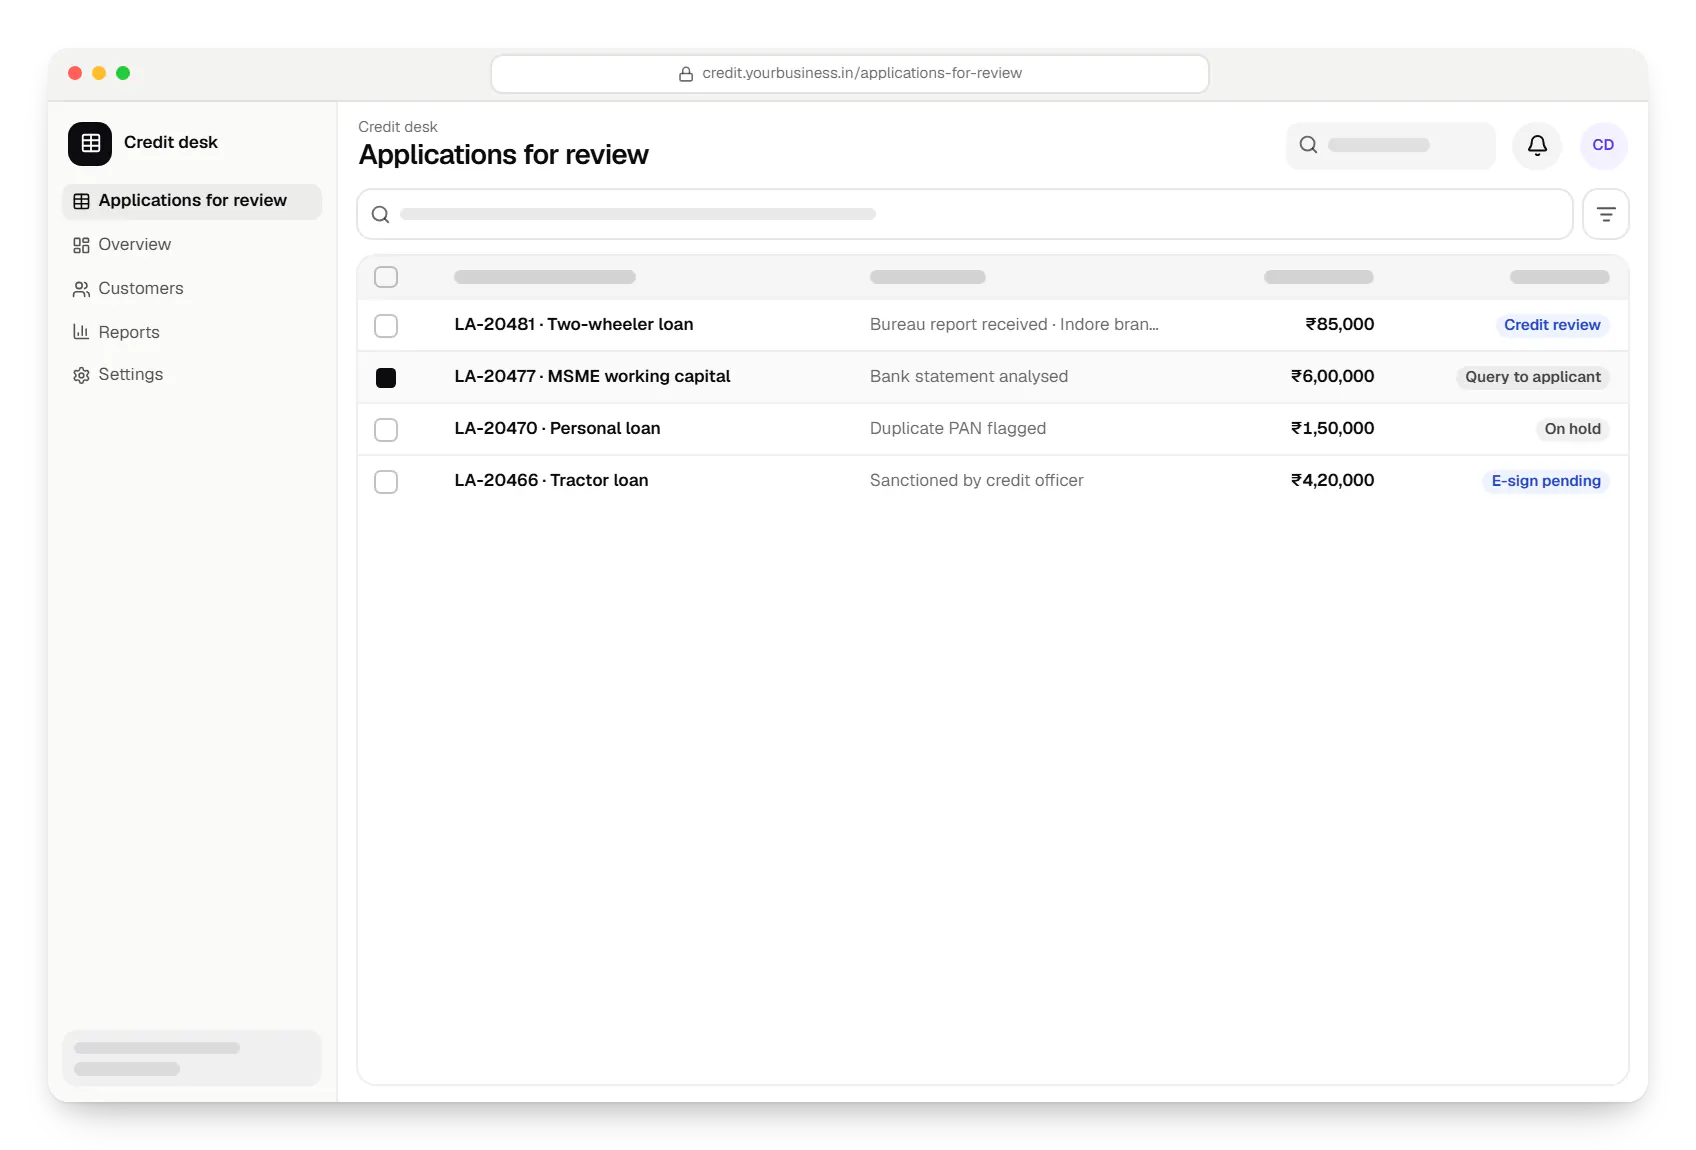
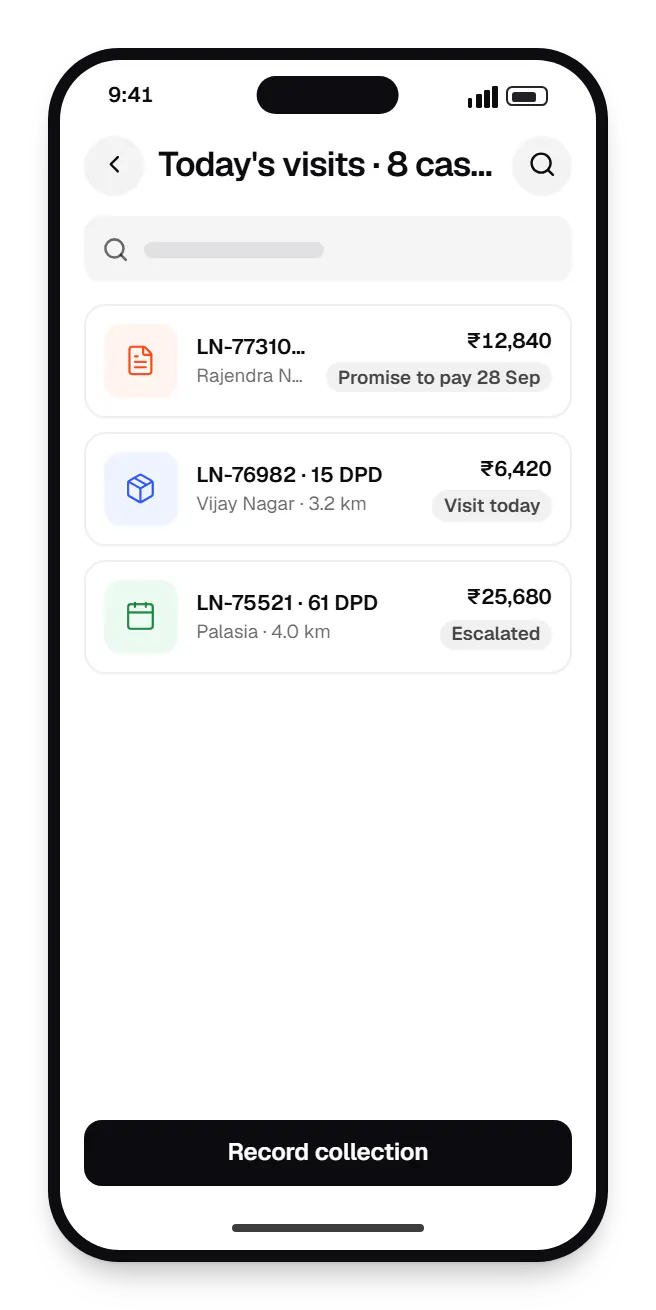
Sample screens: names, prices and figures are examples, not client data.
Industries
Cost drivers
Each product brings its own schedule, charge and accrual rules.
An LMS alone is a smaller scope than end-to-end LOS plus LMS.
Split ledgers and partner reporting add significant logic.
Moving active loans with accurate outstanding balances needs careful reconciliation.
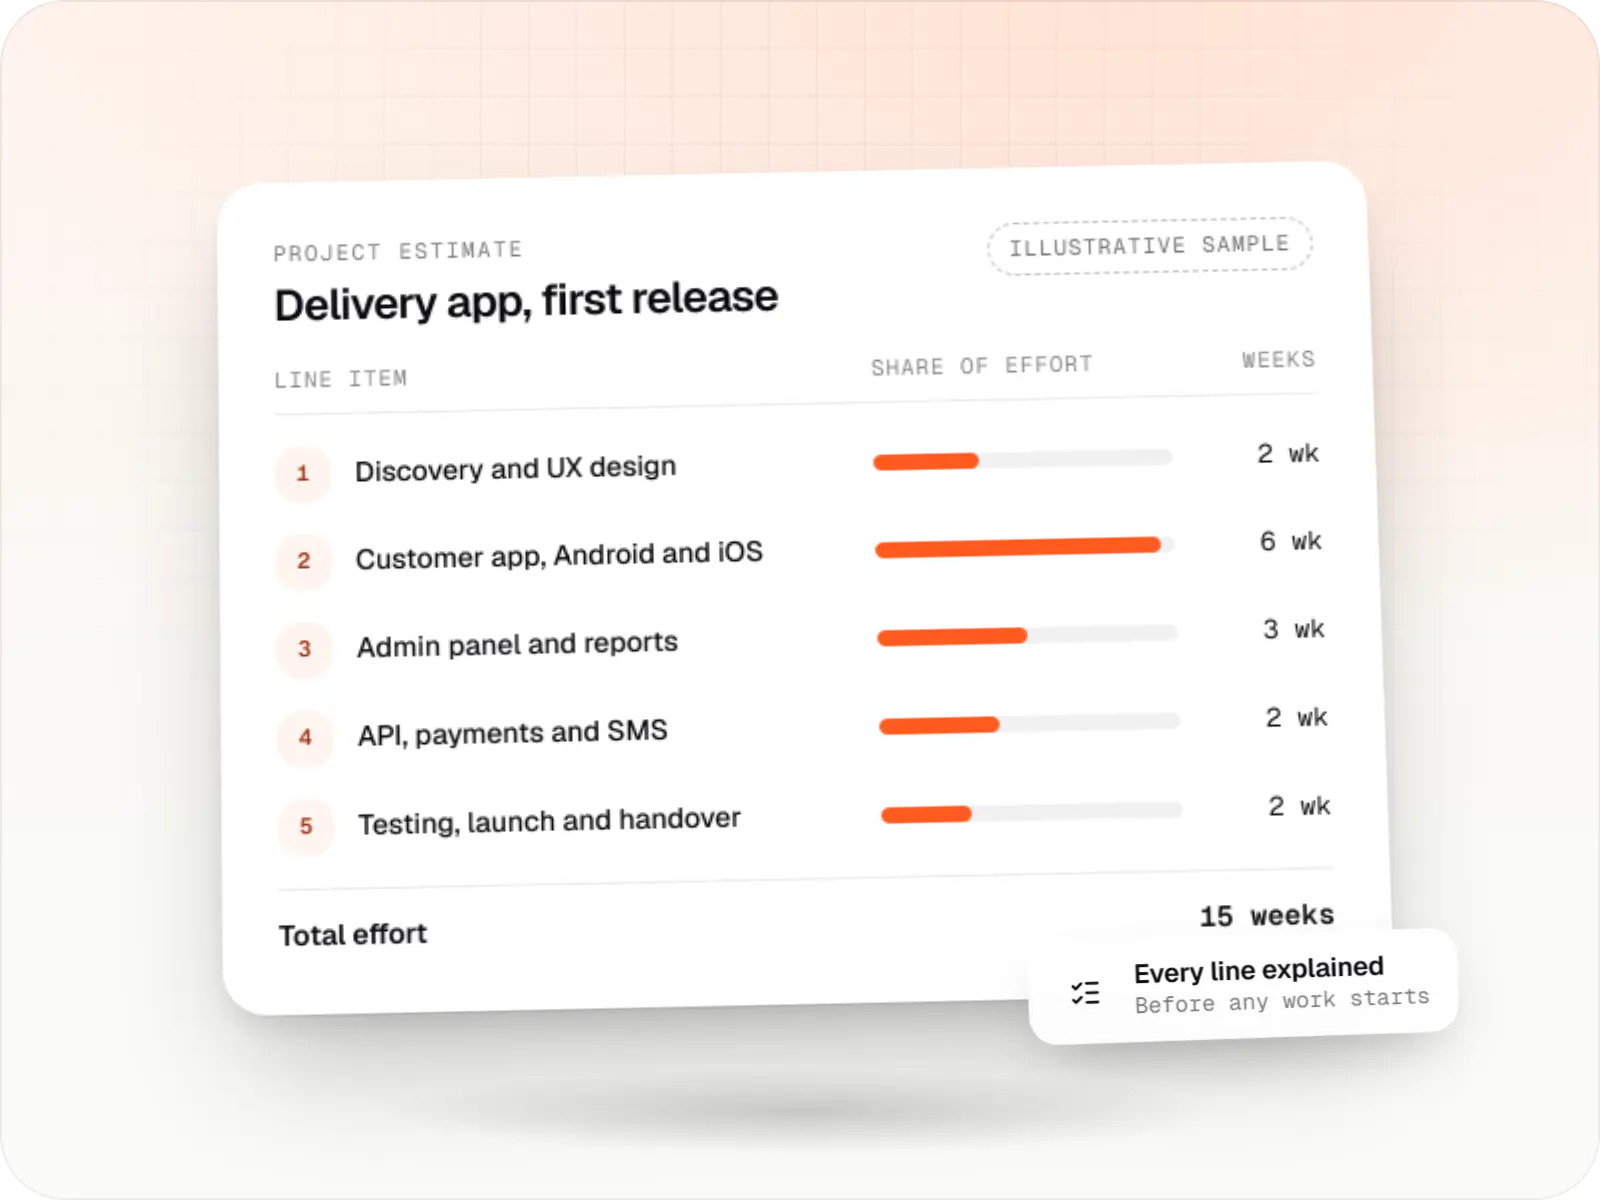
Estimates are written from your scope, with the effort and assumptions behind each line item.
How pricing worksServices
The disciplines a project like this draws on.
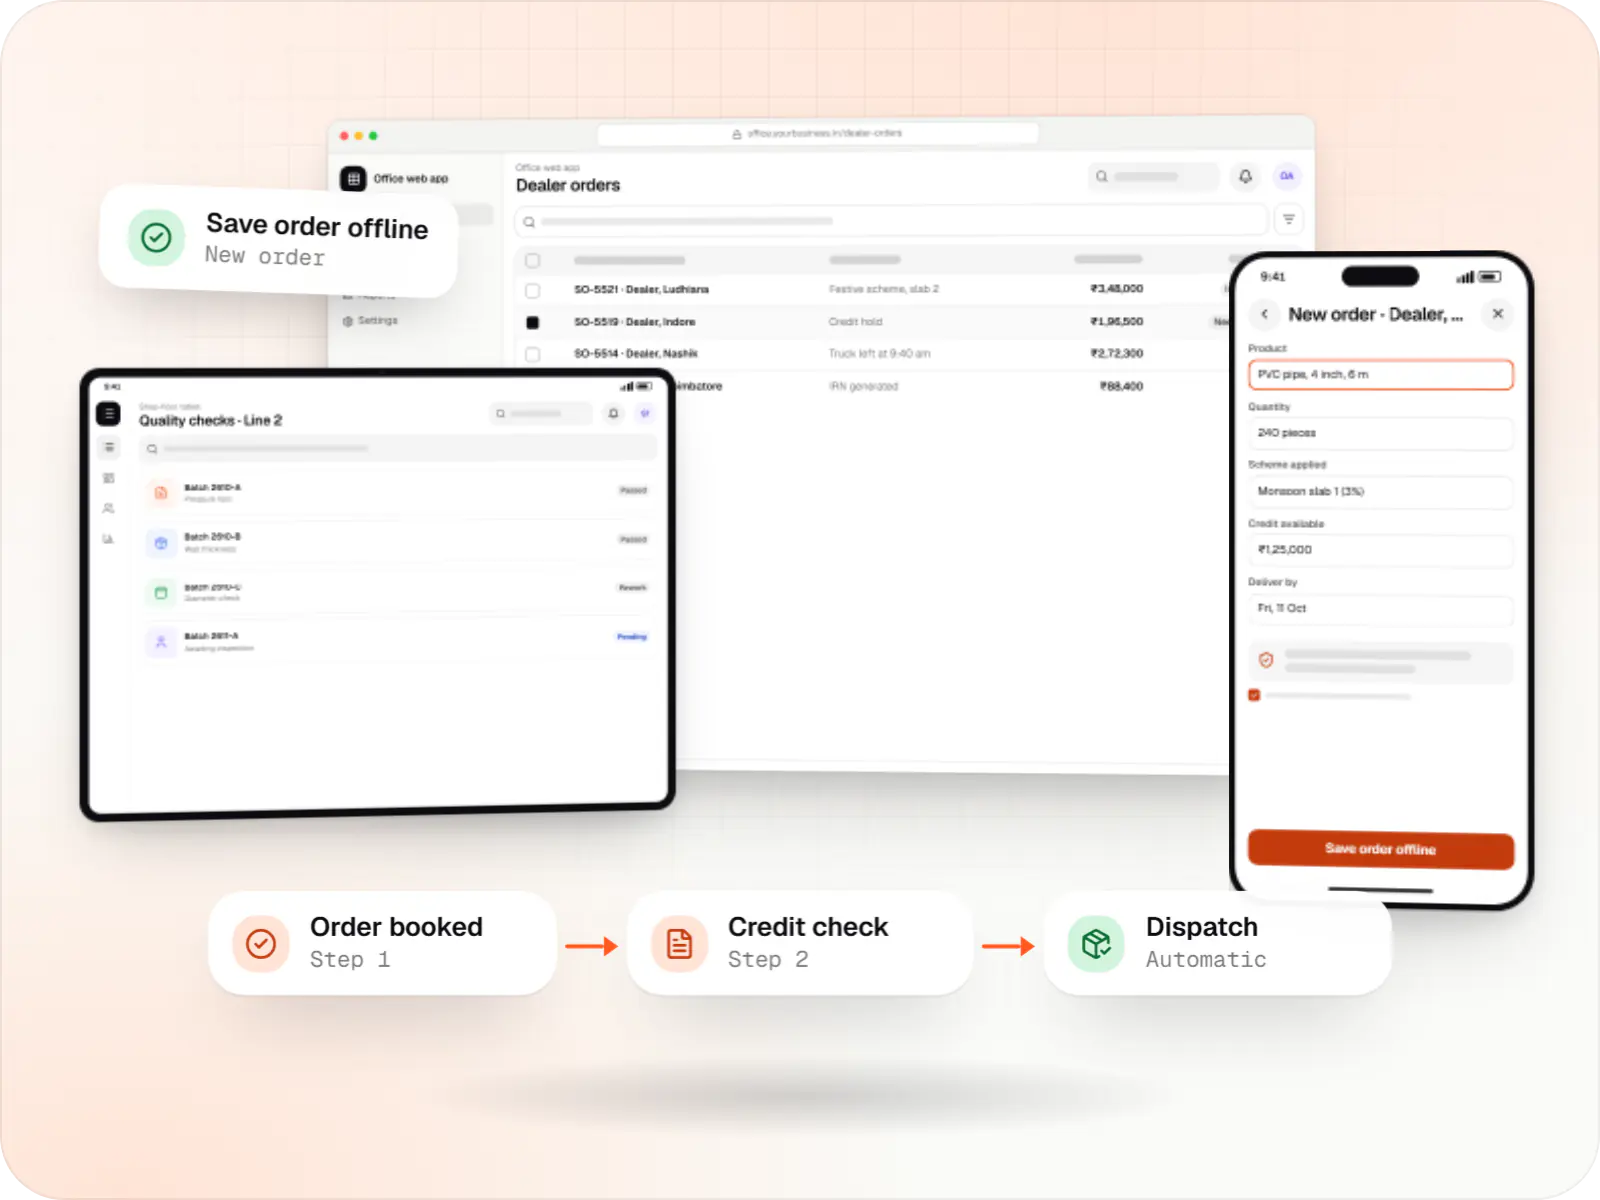
Software shaped around how your business runs, from approvals and inventory to billing and reports, replacing spreadsheets and disconnected tools.
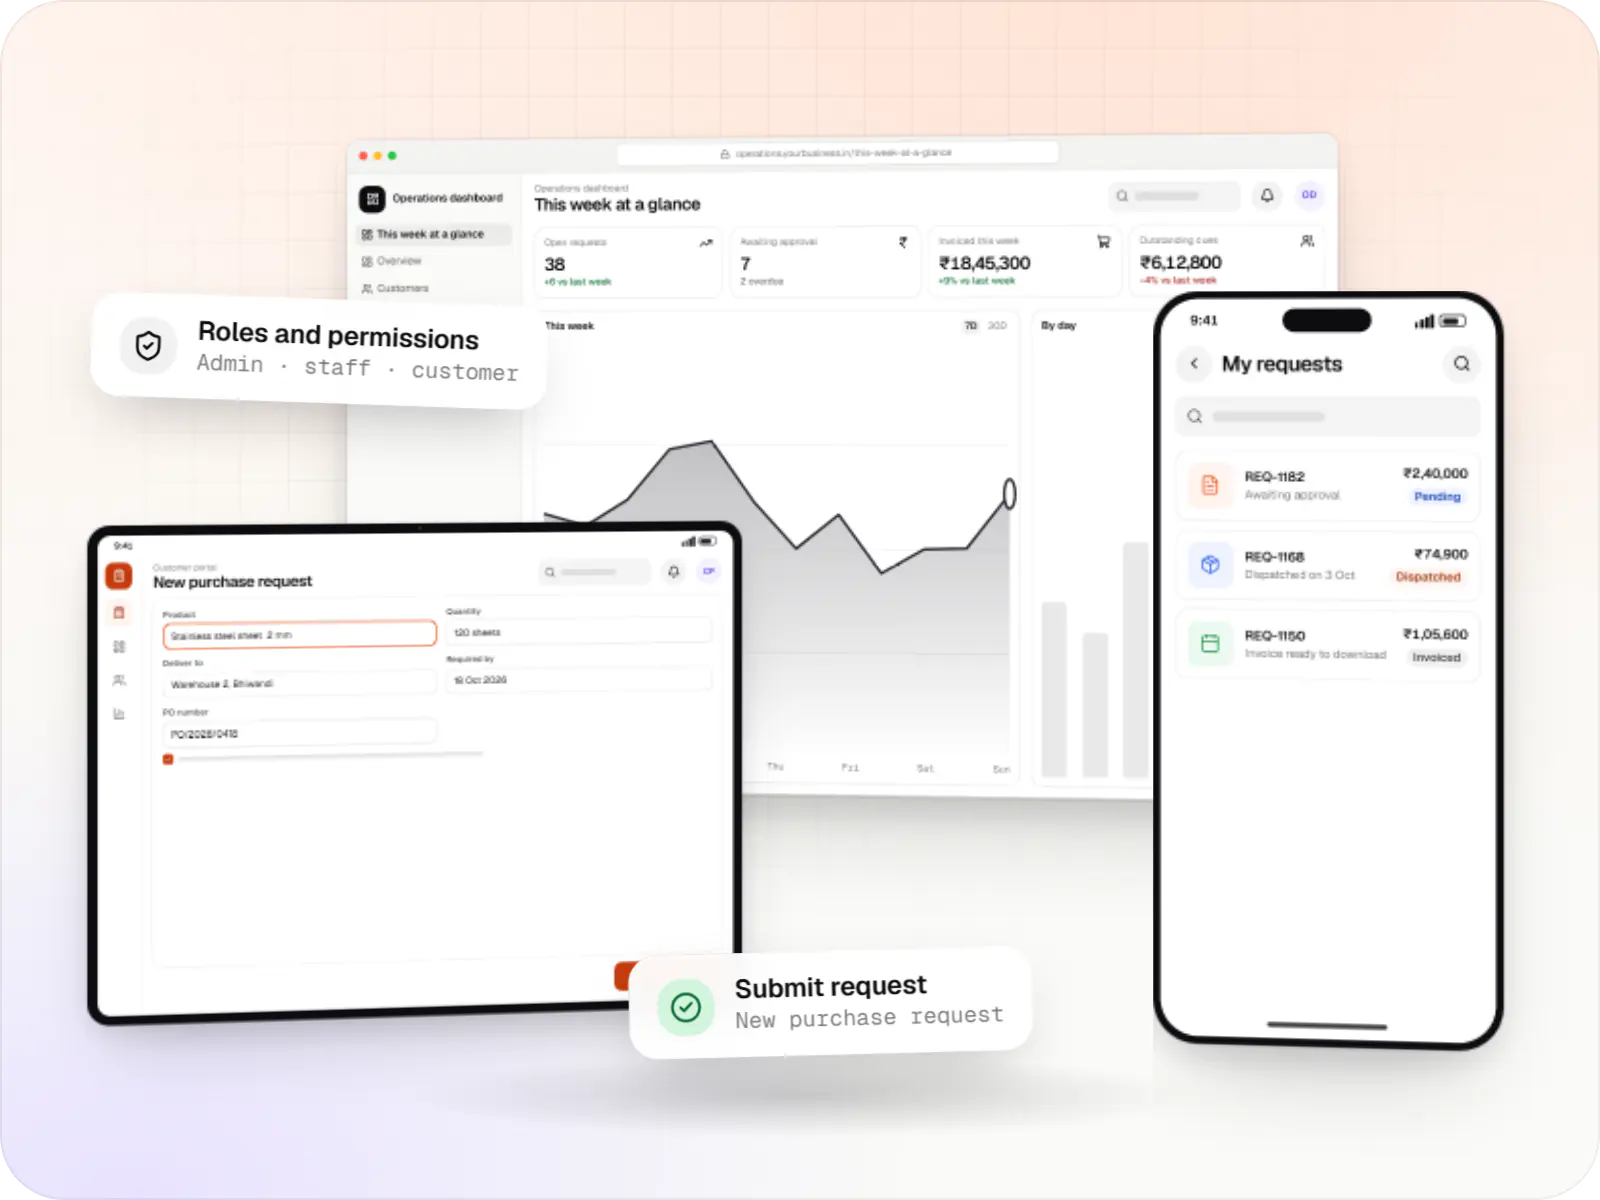
Browser-based products, customer portals, dashboards and internal tools, built on clean data models with secure roles and integrations.
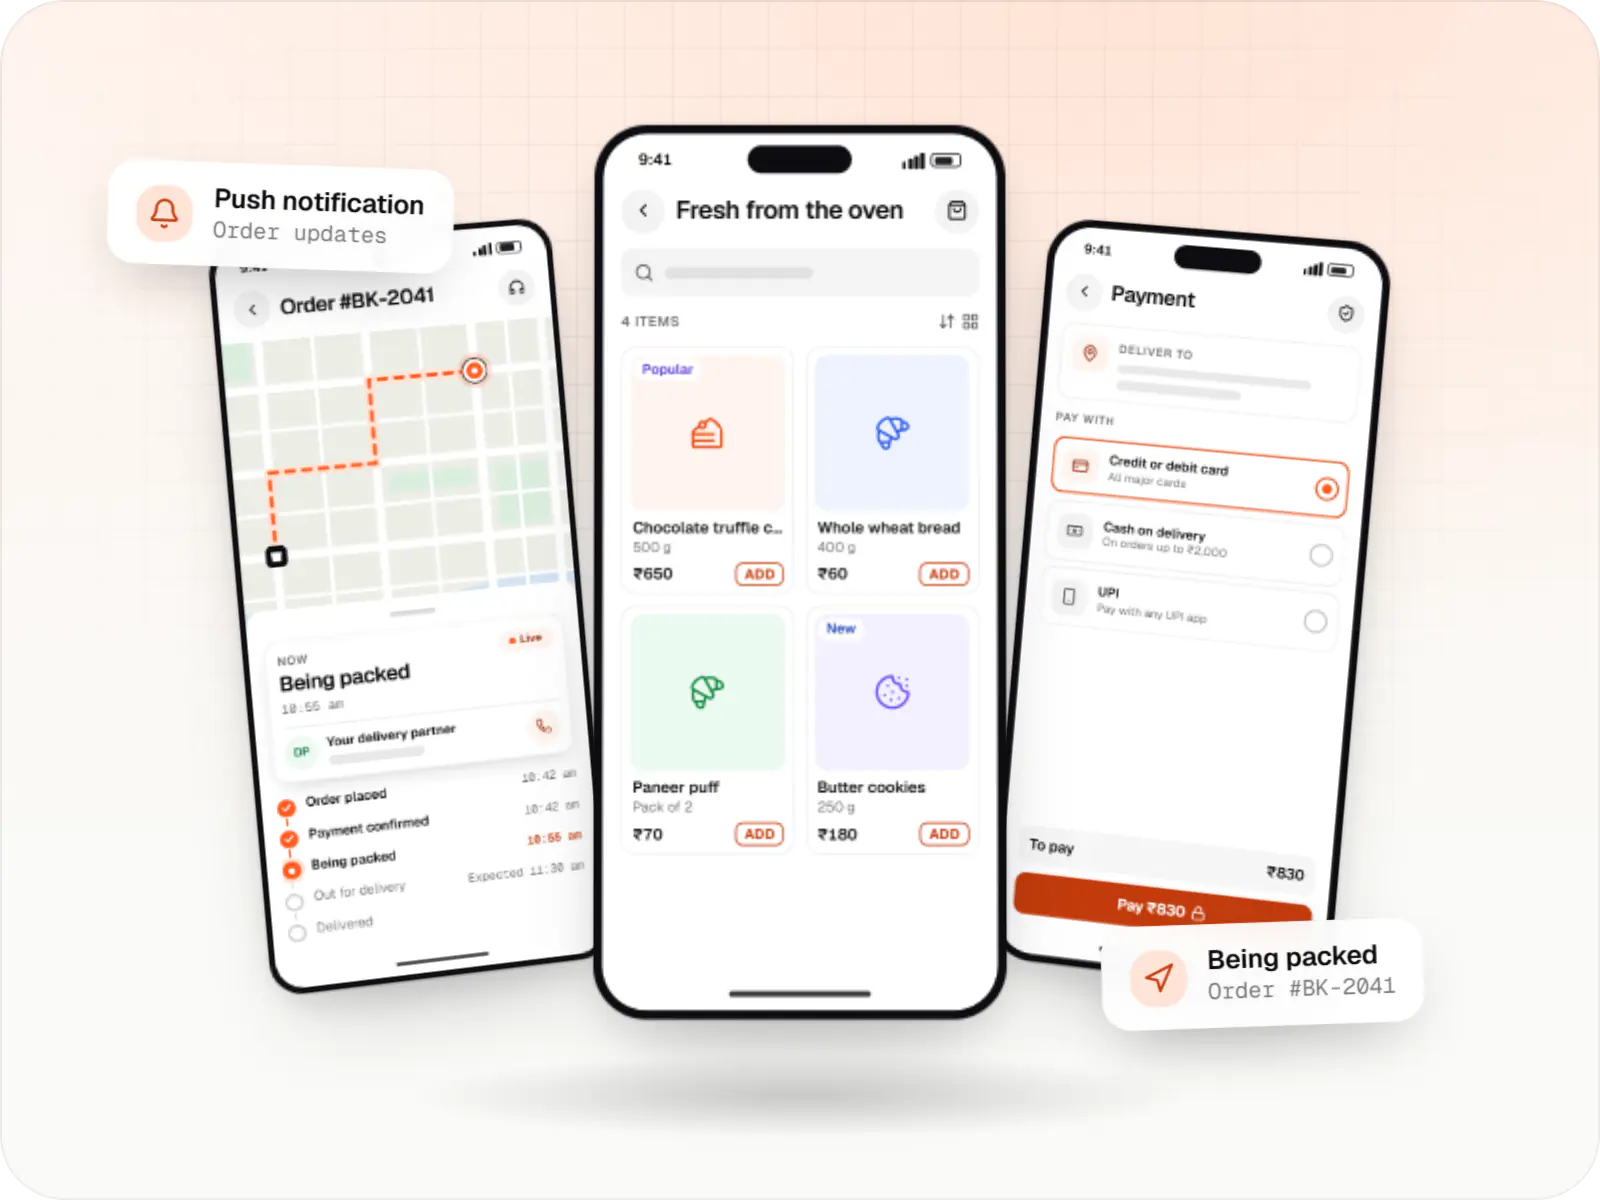
Native and cross-platform Android and iOS apps, from first release through regular store updates, built by our in-house designers and engineers.
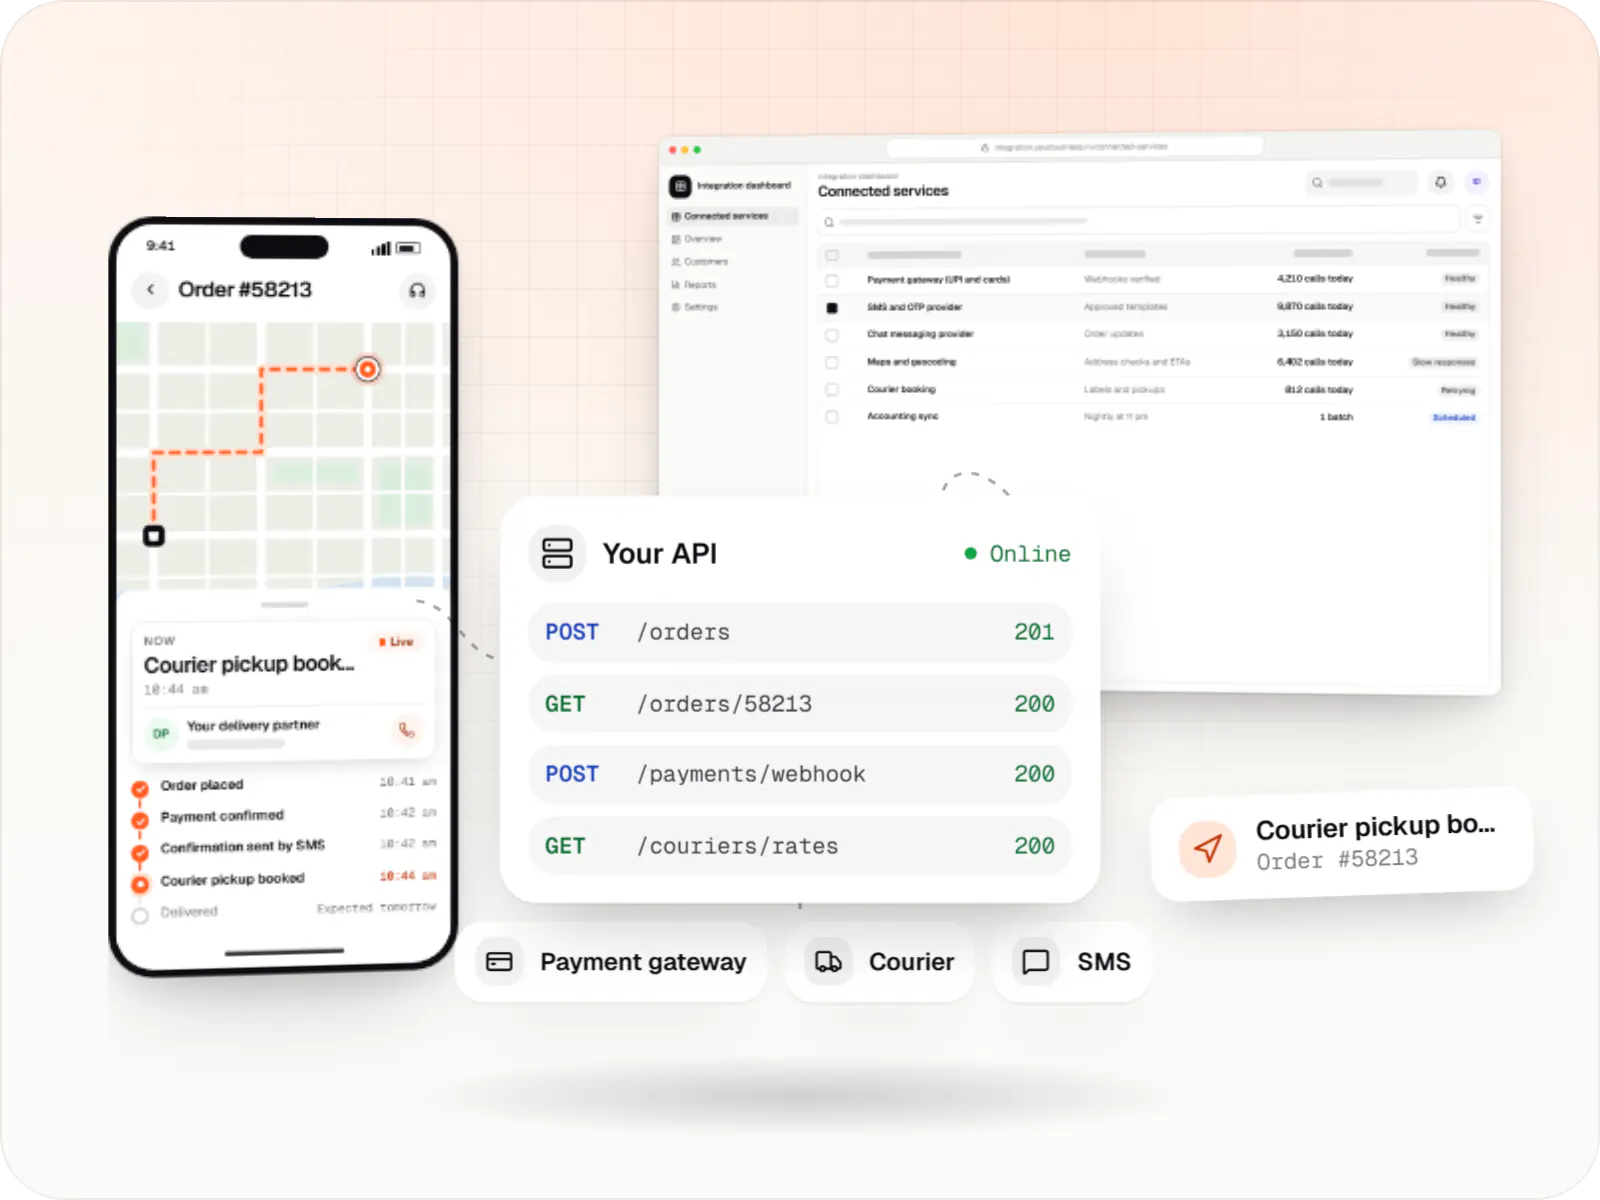
Secure, documented REST and GraphQL APIs, plus integrations that connect your apps to payment, logistics, GST, messaging and business systems.
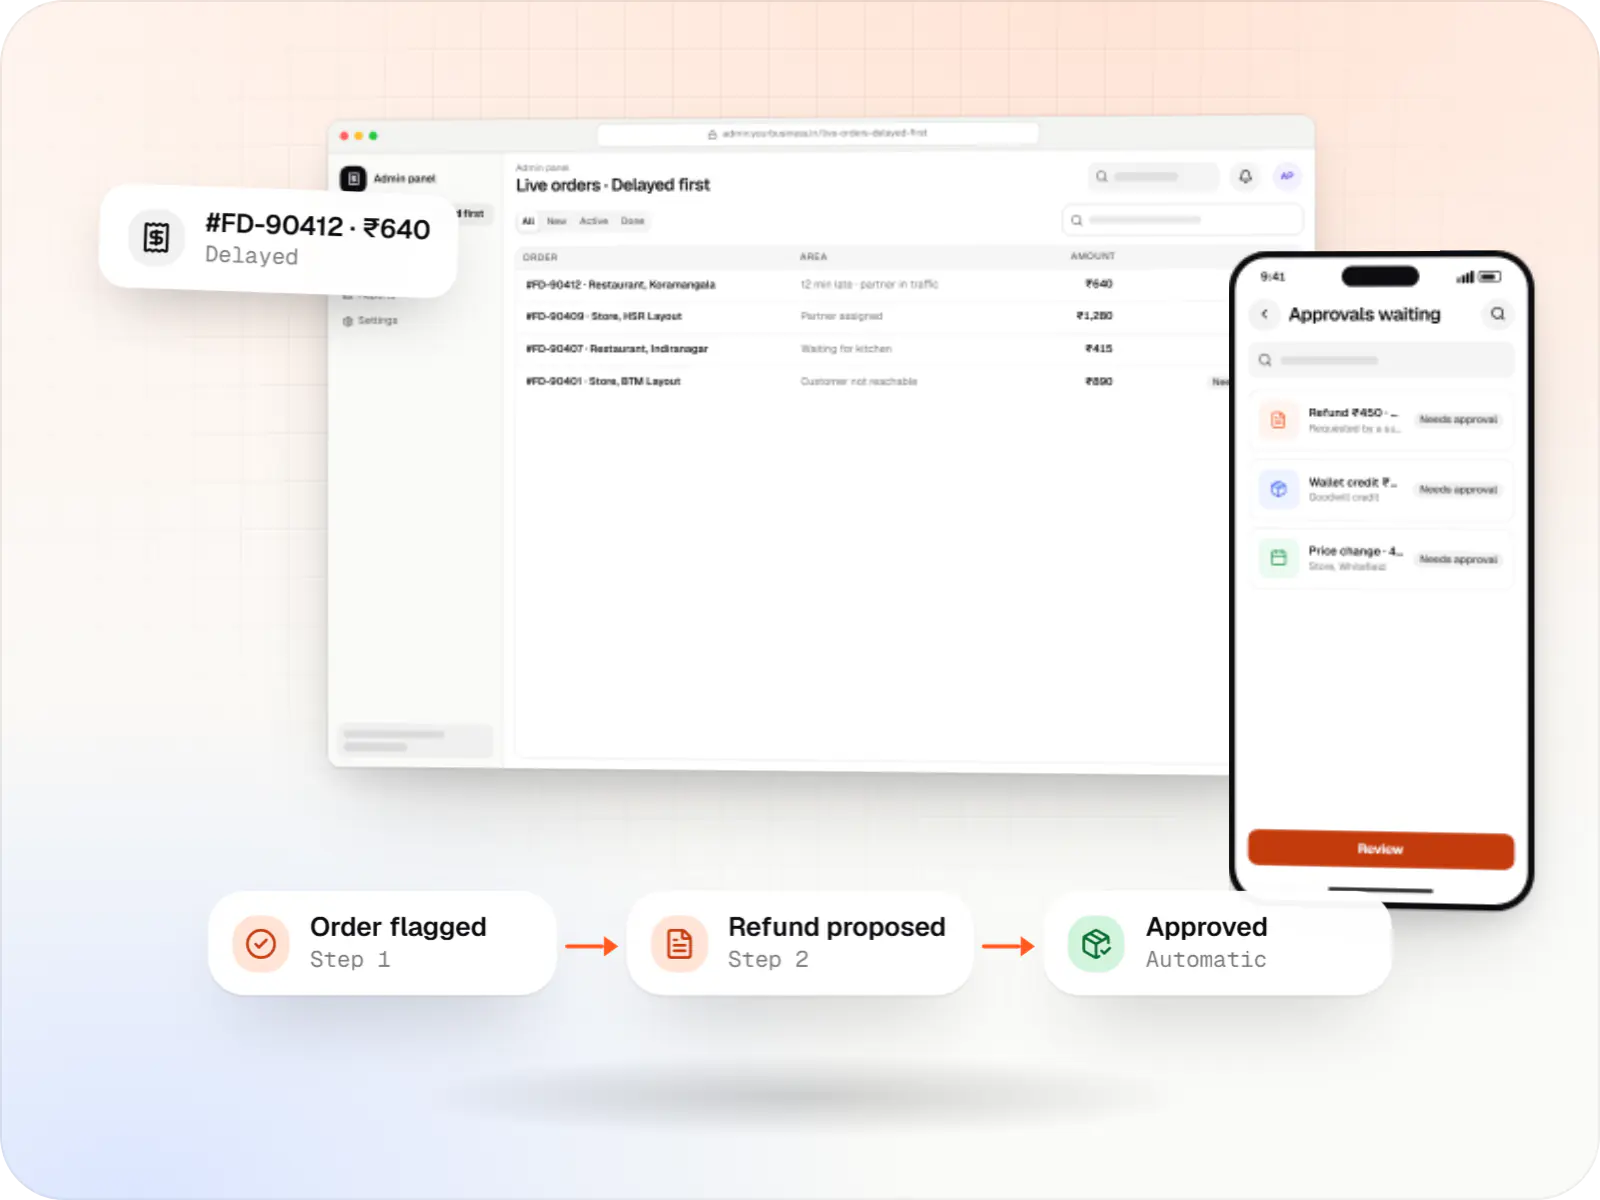
Back-office dashboards built around your team's daily tasks: order queues, approvals, catalogue management, payouts, reports and audit logs.
FAQ
Yes, and we treat it as a project of its own. Each active loan is imported with its terms, schedule, payments, charges and current DPD, and the system recalculates outstanding balances to compare with your records. Differences are listed loan by loan for your finance team to resolve before cut-over. We migrate a sample first, then the full book, and run both systems in parallel for a cycle.
It can. Each loan records partner shares of principal and interest, and every repayment, charge and waiver is split according to the agreement. The system produces partner-wise statements and settlement files, and exchanges loan data through the partner's APIs or files. Co-lending agreements differ widely, so we model them from your actual contracts rather than a fixed template.
Your compliance team interprets the guidelines for your business model and gives us the requirements; we build and document them. Typical examples are generating the key fact statement before execution, disbursing and collecting directly between the borrower's and lender's bank accounts, showing grievance officer details, supporting the cooling-off period and limiting app permissions. We keep a traceable list linking each requirement to its implementation.
Licensed lending platforms can be quicker for standard products and come with established reports. A custom build suits lenders with unusual products, such as crop-cycle repayments, supply chain finance or embedded credit, several co-lending partners, or a need to own the platform. A middle route is licensing a core ledger and building custom origination and collections around it. We will help you compare the options honestly.
Related
Next step
Share your loan products, volumes and partner arrangements. We will propose an origination and servicing roadmap with a line-item estimate.